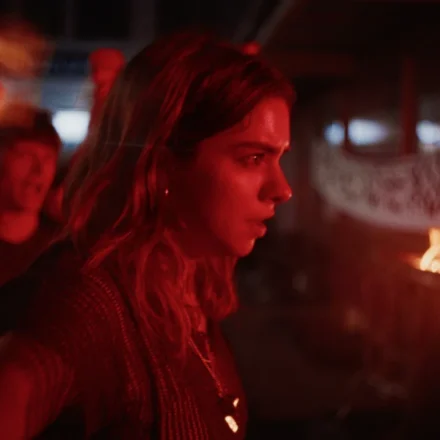
China’s Box Office Faces Post-Holiday Chill as ‘Resident Evil’ Maintains Dominance

The mainland China theatrical market is currently navigating a period of significant cooling, as evidenced by the latest weekend box office figures. For the period of October 23–25, the total market haul slumped to a muted $18.6 million, underscoring a pronounced post-holiday hangover. Despite the overall lack of momentum, Constantin Film and Sony Pictures’ horror reboot, Resident Evil, managed to secure the top spot at the mainland China box office for the third consecutive weekend.
While individual titles continue to demonstrate longevity, the broader cinematic landscape is grappling with a 29.1% deficit compared to the same period in 2025, with the 2026 year-to-date total sitting at $4.7 billion.
The Reign of the Undead: ‘Resident Evil’ Holds Steady
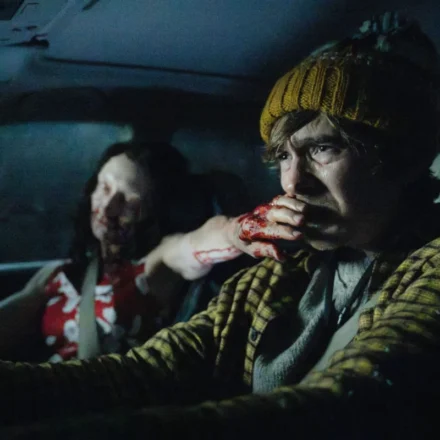
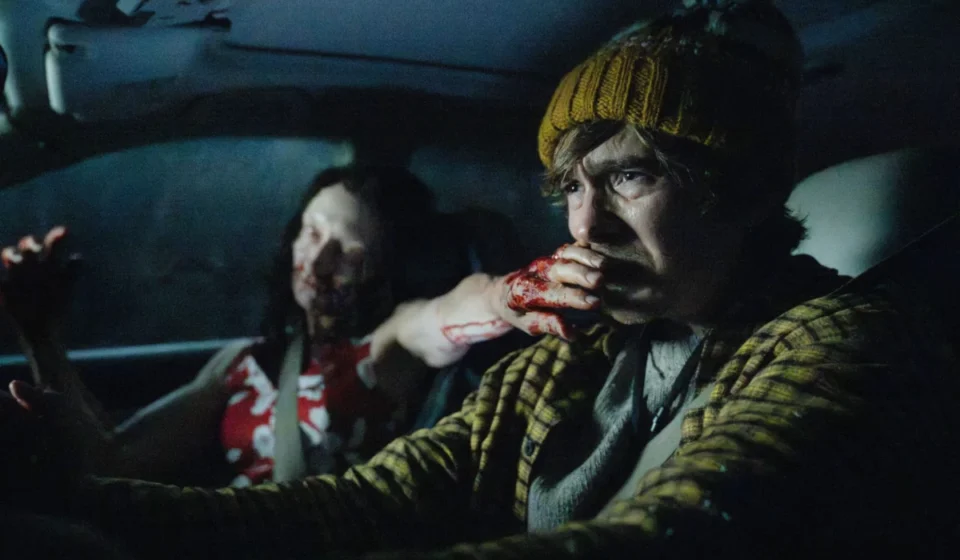
The horror reboot Resident Evil has defied the typical rapid-decay trajectory of genre films in the Chinese market. During the October 23–25 frame, the film grossed RMB 37.6 million ($5.6 million). Since its strategic rollout during the lucrative Golden Week holiday corridor on October 5, the film has cemented its status as a commercial powerhouse, accumulating a cumulative haul of $64.8 million.
Industry analysts point to the film’s strong brand recognition and its ability to capture the post-holiday demographic as primary reasons for its sustained success. By maintaining the top position for three weeks, Resident Evil has outperformed expectations, proving that international horror franchises still hold significant appeal for the Chinese theatrical audience, even in a saturated market.
Chronology of the Top Five
The Chinese box office landscape is currently defined by endurance rather than fresh breakouts. Below is the breakdown of the top-performing films during the recent weekend:
1. Resident Evil ($5.6 Million)
Holding the crown for the third week, the film continues to benefit from limited competition in the horror space. Its $64.8 million total since October 5 positions it as the standout success of the autumn season.
2. Traces of Justice ($4.7 Million)
In its fourth weekend, New Classics Pictures’ crime procedural Traces of Justice maintained its hold on second place. Directed by the visionary Chen Sicheng—known for the blockbuster Detective Chinatown franchise—and co-written with Zhang Ji and Yan Zijie, the film has become a critical and commercial staple. Since its October 1 premiere, it has amassed $92.4 million. The period investigation epic, featuring a star-studded cast including Zhang Yi, Ma Li, and Chen Minghao, with guest appearances by high-profile talent such as Karry Wang, Fan Chengcheng, and Chen Feiyu, offers a multi-decade look at elite public security efforts in China.
3. Mr. & Mrs. Pardon ($2.6 Million)
Beijing Joy Fun Pictures’ body-swap comedy remained in third place. With a cumulative gross of $55.5 million, the film continues to resonate with audiences looking for domestic escapism. Directed by Shen Chunyang and written by Ma Duo, the film leans heavily on the chemistry of its lead stars, Shen Chunyang and Xiao Shenyang, who are a real-life comedic power couple. By exploring the complexities of domestic friction through the lens of a body-swap narrative, the film maintains a steady, if modest, pace.
4. Once Upon a Time in the Middle East ($800,000)
A testament to the "long-tail" effect, Dirty Monkeys’ war comedy-drama is now in its eleventh week of release. While its weekly take has slowed to $800,000, the film has achieved a remarkable cumulative total of $355.5 million since its August 11 debut. Directed by Wen Muye, the filmmaker behind the massive hit Dying to Survive, the film features a high-wattage cast led by Shen Teng, Jiang Qiming, Aarif Rahman, and Omar Sherif.
5. All Wishes Come True! ($600,000)
Rounding out the top five is Pearl Studio’s computer-animated fantasy comedy. After 15 weeks in release, the film remains a family-friendly staple. With a weekend haul of $600,000, it has reached a cumulative total of $306.6 million, proving that high-quality animation remains one of the most reliable pillars of the Chinese theatrical economy.
Supporting Data: A Market in Contraction
The data provided by Artisan Gateway highlights a stark reality for exhibitors. The total weekend box office of $18.6 million is emblematic of a "muted" period following the high-intensity traffic of the Golden Week holidays.
The year-to-date performance is perhaps the most concerning metric for stakeholders. With a 2026 total of $4.7 billion, the market is currently tracking 29.1% behind 2025’s figures. This shortfall suggests that while individual films are performing well, the total volume of ticket sales is not recovering at the pace required to meet the high benchmarks set by the previous year. Factors such as shifts in audience behavior, a change in the cadence of major blockbuster releases, and increased competition from alternative entertainment platforms are likely contributing to this downward trend.
Official Perspectives and Industry Sentiment
While specific studio responses to the recent weekend figures have been limited, the sentiment among distributors and cinema chains is one of cautious optimism. The success of Resident Evil suggests that when a film aligns with current audience appetites, it can sustain interest for weeks. However, there is a recognized need for a stronger pipeline of tentpole films to bridge the gap between holiday windows.
Market experts observe that the "post-holiday slump" is a natural cycle, but the depth of the current slump is deeper than historical averages. The industry is looking toward the upcoming winter season, traditionally a period where romantic dramas and action-heavy spectacles are released, to reverse the negative growth trajectory.
Implications for the Future of Chinese Cinema
The current box office landscape offers several key insights into the future of the Chinese market:
1. The Power of Longevity
The success of films like Once Upon a Time in the Middle East and All Wishes Come True! proves that Chinese audiences are willing to sustain films for months if the word-of-mouth remains positive. The era of the "three-day opening weekend" is being challenged by films that possess long-term staying power.
2. Genre Diversity is Essential
The top five list features a diverse array of genres: horror, crime procedural, body-swap comedy, war drama, and animated fantasy. This mix indicates that the market is not dominated by a single style of storytelling, which provides a level of stability for theater chains attempting to attract varied demographics.
3. The Need for Market Stimulus
The 29.1% year-to-date deficit is a wake-up call for the domestic film industry. To close this gap, stakeholders are likely to focus on several strategic adjustments:
- Targeted Marketing: Leveraging the influence of actors like Karry Wang or Fan Chengcheng, as seen in Traces of Justice, to drive younger audiences into theaters.
- Strategic Scheduling: Avoiding "dry spells" by spacing out major releases more evenly throughout the year, rather than clustering them solely within holiday corridors.
- Enhanced Distribution: Increasing the availability of premium large-format (PLF) screens for high-performing titles to maximize revenue per screening.
4. International Collaboration
The success of Resident Evil reinforces the viability of international co-productions or high-profile imported content within the mainland market. As the industry looks to recover from the 2026 slump, the balance between supporting domestic hits and maintaining a diverse slate of international imports will remain a delicate but vital component of commercial success.
Conclusion
As China moves into the final months of 2026, the theatrical sector remains in a period of transition. While the current box office figures reflect a necessary cooling period, the continued performance of veteran hits like Once Upon a Time in the Middle East and the surprising stamina of Resident Evil provide a roadmap for survival. The challenge ahead lies in revitalizing the market’s pace to ensure that the year ends on a trajectory that minimizes the current 29.1% gap, setting a more robust foundation for the industry as it moves into 2027. For now, cinema operators will continue to rely on the endurance of the current top five to keep the lights on until the next wave of major releases hits the big screen.